Showing posts with label CPF. Show all posts

Saturday, 25 March 2017

When is the best time for making OA to SA transfer | Earlier is not always better


Few months back Max wrote a post to discuss the things to consider before transferring our CPF money from OA to SA savings. Essentially, the post discussed that if the transfer is made earlier, the power of compounding at the higher interest rate will reap significant benefits, but because the transfer is irreversible, the 'in case I need it' mentality is still the key barrier for some to optimize their CPF savings.

Majority of us (if not all) understand the principle that we should make the transfer early for CPF optimization. This statement is absolutely correct. But do you know, if we add our cash savings into consideration, there will be unique cases which we should delay the OA-SA transfer.

Yes you heard me right, D-E-L-A-Y. Something new huh, let's proceed.

Saturday, 25 February 2017

CPF Retirement Sum Scheme | Can I achieve the CPF retirement sum when I reach 55?

The CPF Retirement Sum Scheme is one of the CPF schemes for us to utilize the money in our CPF. In fact, in my opinion, it is the most important CPF scheme as it will determine the 'fate' of the savings we painstakingly built up throughout the working life.

Unless we are approaching the magic number of age 55 to be eligible for CPF withdrawal (after setting aside the Retirement Sum), chances are we will not be able to determine the amount of CPF savings we will have by then. Furthermore, there involve an uncertainty with the expected annual increase in the Retirement Sum. 

This makes many Singaporeans wonder if they will ever have enough CPF savings to withdraw a lump sum when they reach 55. Let's get down to it.


Adapted from CPF website


How much monthly payout will I receive at age 65?

The amount of retirement savings to set aside depends on a few criteria, including the amount we have in RA savings at age 55, whether there is sufficient property charge/ pledge, etc. For readers who are not familiar in this area, MoneySmart Blog has written a concise but comprehensive article here.

In brief, there are three tiers to the Retirement Sum:
  • Basic Retirement Sum (BRS), 
  • Full Retirement Sum (FRS) which is 2 times the BRS, and 
  • Enhanced Retirement Sum (ERS) which is 3 times the BRS
For this article, we will discuss mainly using the FRS as a reference.

The amount of retirement savings will also directly affect the amount of monthly payout members can receive from age 65. To compute the estimated monthly payout receivable at age 65, we can use the LIFE Payout Estimator available on the CPF website.

For a quick estimate, Max has compiled some output using the calculator with results presented in the table below. 

Graph 1: CPF LIFE monthly payout vs RA savings at age 55/65


Just for a quick illustration, if we have $200k in our RA savings at age 55, based on the CPF calculator, the monthly payout expected at age 65 will be $1,523*. Using the orange line in the chart, this information can be determined by simply referencing the RA amount on the X-axis, to the monthly payout on the Y-axis. 

*The amount shown in CPF calculator is a range from $1,523 - $1,678 using the LIFE Standard scheme. To be conservative, the lower amount is used for the chart above.

In fact, the correlation between our RA savings and the CPF LIFE monthly payout is linear, which should not come as a surprise to us. 

To get a rough estimate for the expected monthly payout from age 65 onwards, we can simply multiply 0.007 to the RA amount we have at age 55. This is also valid for the blue line for RA savings at age 65, by simply using a different multiplier of 0.005. 

This means that if we have $100k in our RA savings at age 65, we can expect a monthly payout of $500 (0.005 x $100k) under the LIFE Standard scheme.

How much will the Retirement Sum be when I reach 55?

According to CPF website, the retirement sum has increased yearly "to cater for long term inflation and increase in standard of living". As of the point of writing, the Full Retirement Sum (FRS) for 2020 is set at $181,000, which is about an annual increase of 3% from the $166,000 currently in year 2017.

From the historical FRS (previously known as the Minimum Sum), the average rate of annual increase from 2003 to 2020 is 5.24%. Personally, Max does not expect the FRS to continue increasing at this rate. In fact, the recent rate of increase has stabilized to around 3.0% per year. 

For completeness of the analysis, the chart below shows the FRS forecast based on both 3.0% (orange line) and 5.24% (blue line) rate of increase.

As we can see (assuming the 3.0% increase is maintained), the FRS will be about $300-400k in 20-30 years' time. This is not a small sum, can we even achieve it? Let's read on. 


Graph 2: CPF Full Retirement Sum forecast

Will my RA savings exceed the FRS when I reach 55?

This is the most important question of the entire article. Ultimately, annuity in the form of CPF LIFE payout will not feel as satisfying as receiving a lump sum of cold hard cash at age 55.

Fundamentally, in order to withdraw money from our CPF after years of working, our RA savings at age 55 must be more than the FRS (or BRS).

To answer this question, we must first agree that the total RA savings is dependent on
  1. Monthly income (eligible* for CPF contribution)
  2. Annual bonus (eligible* for CPF contribution)
  3. Years of active employment - some work for 40 years, some wants to retire by 40
  4. Utilization of CPF savings - for public housing, education, investment etc.
  5. CPF top ups using cash
  6. Transfer of OA savings to SA

*There is a limit to how much our annual income is eligible for CPF contribution, which is stated in the CPF contribution ceiling. This means that if your income hit a certain limit, the additional wage will not be eligible for CPF contribution (from both employer and employee).

For simplicity, let's look at the following scenario:

Joe is a 25 yo fresh graduate (with zero CPF savings) who started working in year 2017 and intends to stop working by age 55. He receive a monthly gross income of $3.0k, with an expected yearly increment of 3.0% throughout his employment, and an annual bonus equivalent to his 1 month's income. 
Joe has successfully applied for a $500k BTO, expected to be ready by age 30, with the down payment and monthly installment to be split evenly with his spouse. How much savings will Joe have in his RA account when he reach 55 yo?

This look like a Primary 6 exam question, but Max is sure most people will not be able to, or will not be bothered to find the answer (even if I change Joe to 'your name'). But to be fair, there is no simple formulas to compute the answer, so Max has added this capability into his Financial Independence Model (FIM) to 'model' the answer. The answer for Joe will look something like the table below. 


Joe will have about $433k in his RA savings when he reach 55, which is about $18-19k more than the estimated FRS at $414k. Depending on whether Joe would like to maintain his Retirement Sum at BRS or FRS, he can withdraw $18k (about $8k in today's dollar) or more from his CPF.

Joe will receive about $3.4k (slight above $1k in today's dollar) per month under the CPF LIFE scheme when he reach 65 yo. 


How to have more RA savings by age 55

To have more RA savings by 55, Joe can subscribe to the CPF OA-SA transfer to enjoy higher interest rate on his savings.

For example, if Joe transfer all his excess OA money to SA savings, while ensuring he has at least $10k (adjustable based on individual's preference) in the OA savings at the end of every* year, he will have $478k in his RA savings by 55 yo. That is an additional $45k (or $18.5k in today's dollar) by just making your CPF savings work harder for you. Who says interest compounding is overrated?

*except for the first year of working where the OA savings is still below $10k

Table below generated by the FIM shows details on the amount of money Joe can transfer from his OA to SA savings for each year. In particular, note that the recommended amount to transfer will take the expected future utilization of the OA savings into consideration, to prevent 'over-transferring' and falling into a deficit situation when the OA savings is required. 

This can be seen from age 28 and 30 when FIM suggests that Joe should not make any OA-SA transfer, to ensure that his OA savings is sufficient for the $25k BTO down payment at age 30. 


What about you?

The Retirement Sum will continue to increase to keep up with the higher standard of Singapore's living. Will we have enough CPF savings to meet the Retirement Sum when we reach 55 yo? Max knows he does, what about you?


Saturday, 14 January 2017

Should I transfer money from OA to SA account?

One of the key aspect to achieving early Financial Independence is to optimise the returns of your wealth. However, many people focuses primarily on building up their cash bags and neglect the other bulk of their savings, the CPF.

Although our CPF savings cannot be withdrawn before the age of 55, it is important to start acting early, to take advantage of the risk-free interest rate on our CPF savings. One of the available CPF schemes is to transfer OA savings to SA account (OA-SA transfer).

What is the difference between OA and SA account?

Unless you have just started receiving periodic contributions to your CPF, you deserve a knock on the head for asking this question. Nonetheless, Max has created a simplified poster below to highlight the main differences between the two accounts.


In the discussion to accelerate growth of your retirement savings, the higher interest rate earned by the SA account is the key variable to the equation. In return, we give up flexibility as the SA account cannot be utilize for Housing and Education, which are two big expenses we cannot ignore. 

In case I need it (ICINI)

Stop using 'in case I need it' as an excuse, this is the main killer to optimisation of wealth. The same meaning as 'in case' is 'I did not plan'. 


If you do not plan, you plan to fail. Okay, cliche, but it's true. 

Will you pay for something you don't need?

I am quite sure the answer is no. That is why we picked a suitable phone mobile plan that offers sufficient but non-excessive free data plan. Similarly, we cancel credit cards that we do not use to avoid paying the subscription fee. 

In both cases, we are unwilling to pay for unnecessary services/ conveniences because we can evaluate our needs, to decide an appropriate level of comfortable sufficiency. 

Then why should we 'pay' for excessive flexibility to utilise our CPF savings? If we can take some time to evaluate our demand for the OA savings now, the excess savings can then be transferred to the SA account to earn a higher interest. It's all about advanced planning to get more out of our retirement money. 

How much more interest? (2.5% to 4% only, not much right?)

This extra 1.5% makes all the difference, especially if time is on your side. The earlier the transfer, the additional interest will be (increasingly) higher.

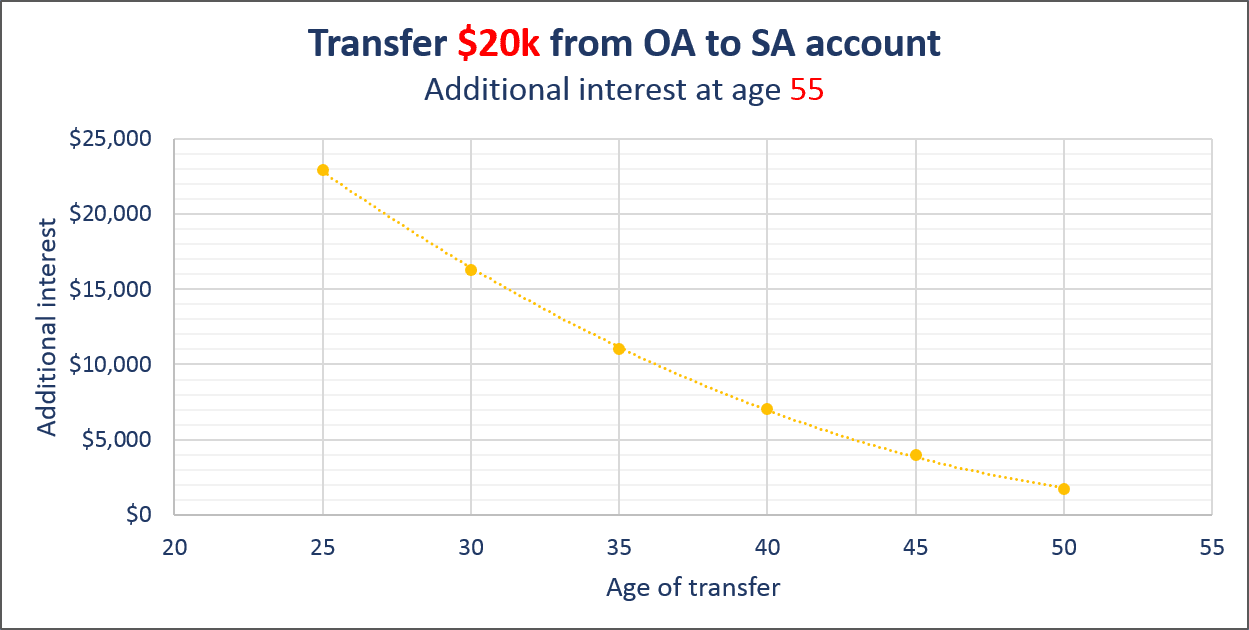
If you are interested to know the amount of additional interest you can receive at age 55, take a minute to study the graph below. A typical 30 yo working adult will earn an additional $16k in interest by age 55, if he transfers $20k from OA to SA account today. This is effectively a 80% 'returns' on your unused OA savings. If the transfer is done earlier, the amount will be higher, and vice versa.


As you can see, as your age increases, the additional interest decreases more quickly if you delay the transfer by a year. This is the power of compounding. So, to get more out of the transfer, act early, don't procrastinate.

In the graph, 55 yo is used as the reference because that is the age we can withdraw our CPF savings, after setting aside the Minimum Sum. That means, the additional interest you received can be withdraw as cash when you hit 55 years old. These are 'free' money with just a few clicks on the CPF website.

CPF website has a calculator to compute how much more interest you can get from a OA-SA transfer. Check it out here.

What is stopping us?

Okay I exaggerated, the process might be simple, but the planning behind the decision to transfer money from OA to SA account requires more brain juice. Indeed, it is not a simple decision, even Max took a few days to consider before transferring $25k of his OA savings to SA account in 2016.

So, what is making the decision so difficult. Max thinks that it all boils down to the lack of knowledge in two areas:
  1. Not knowing the benefits of such transfer
  2. Not knowing how much OA savings is required for longer term purposes (such as housing and education for kids)

If you fall under the first group, I suggest you read the previous to convince yourself on the power of compounding. For the second group, who is also the ICINI group, it is important to carefully evaluate your personal needs for the money in CPF OA account. This is important because the OA-SA transfer is irreversible, which is the main difference with downsizing your phone plan or cancelling a credit card.

How much OA savings do I need?

While the aim is not to allow your unused CPF savings to sit in the OA account earning a lower interest rate, do not also fall into a situation with insufficient OA savings to meet your needs.

To avoid that, we must know what we need, so we plan to ensure sufficiency. To understand your personal needs for OA savings, do consider some of the questions below:
  • At what age do you expect to purchase/ finance your property/ education?
  • What is the cost of the property/ education?
  • What is the upfront payment and monthly payment required? 
  • Financing through CPF OA, cash or a combination of both?
  • Decide whether you plan to invest using CPF? (considering that the investment product applicable for CPF SA is more limited)

Remember to also cater buffer to your plans; things does not always go according to plan. For example, if you are planning for a $300k BTO purchase at 35 yo, it's better to budget for $350k by 33 yo. 

At the same time, try to give a more certain plan by avoiding vague answers such as 'maybe', 'not sure' or 'between 30 to 40 yo'. The more certain you are, the less money you need to set aside as buffer. This means less money can be transferred to SA account, and less additional interests to be earned. Get the idea?

So, should I transfer now?

There is no step by step guide out there <let me know if there are any>, but it is as straightforward as understanding your personal needs, work out the yearly expected contribution and withdrawal from the OA account, before transferring the excess to SA account. Simple, yet not so simple.

In fact, considering all aspects, it is complex enough to need a model for such computation. Max is currently working on a model to answer such questions related to wealth optimization, do subscribe to the blog to be informed when it is ready. It should take another 1-2 more weeks.

Meanwhile, why not take 10 minutes to read the CPF links at the end of the post. It will give you a better idea of how much you need for OA savings. It may give you more cash withdrawal at age 55.

Don't wait, optimize your CPF savings now.

----------
MAFIA
----------

CPF overview
https://www.cpf.gov.sg/Members/AboutUs/about-us-info/cpf-overview

Interest rate for CPF savings
https://www.cpf.gov.sg/Members/AboutUs/about-us-info/cpf-interest-rates

CPF Public Housing Scheme
https://www.cpf.gov.sg/Members/Schemes/schemes/housing/public-housing-scheme

CPF Education Scheme
https://www.cpf.gov.sg/Members/Schemes/schemes/other-matters/cpf-education-scheme

Upcoming posts

1. More about myself - posted on 6 Jan 2017
2. Do you have a plan for early retirement - posted on 21 Jan 2017
3. My financial philosophy
4. Review of my 2016 stock investing performance
5. Why do I top up my CPF SA using cash
6. Big spending - Invisalign

Saturday, 7 January 2017

Are you neglecting your wealth: you have more CPF savings than you think

Let me start this post by the following statement:

At least 31% of your wealth are in CPF

Rub your eyes, stare at the statement again. <No, this is not a typo> If your only source of income is your full-time employment, then a whooping 31% of your income goes to CPF, and the remaining 69% are the cold hard cash you receive as monthly take-home pay. 

Are you kidding me? 31%?

For readers who are convinced, you may skip to the next section. Otherwise, read on for a quick explanation. 

For employee below 55, 20% of your wage will be contributed towards CPF, while your employer contribute an additional 17%. This means that for a person earning $1k per month, take-home pay is only $800, and total CPF contribution adds up to $370; this equates to 69% and 31% respectively. 


In fact, you (very likely) have more CPF than cash savings

Unless you save more than half of your income, I would bet a burger that your total current CPF* saving is more than your cash savings (including cash-equivalent asset such as investment portfolio). 

*Include CPF savings for other purposes (such as property, investment etc.)

This fact may be surprising, but is actually a highly probable situation for many of us, especially for young working adults like Max.

Using the same guy with $1k gross income as example: By saving half of his take-home pay, his total saving is only $400 ($800/2), as compared to $370 of CPF saving. With interest rate of 2.5% and 4% for OA and SA savings, it is not unlikely for CPF savings to exceed total cash savings.

A quick check: as of today, Max's CPF total saving is double of his total cash savings. How does your CPF savings compare with your cash saving? Why not have a quick check? 😎


So, how does that affect me?

With a significant portion of wealth in CPF savings, it is worth putting extra emphasis towards growing our CPF savings.

After all, unless you are able to build up a portfolio huge enough to generate passive income for a comfortable retirement lifestyle, the CPF scheme has to be tap upon to cover the gap.

There are many people (including myself) who can better utilize the relevant schemes to optimize our CPF growth. Some of these (non-exhaustive) are:
  1. CPF investment scheme: investing OA and SA account
  2. Transfer savings from OA to SA account
  3. Voluntary cash top up to SA account

Better don't touch my CPF leh

I am sure many people are not actively trying to maximize their CPF savings due to a lack of financial know-how to evaluate their needs. This is especially true as these decisions made are irreversible. Indeed, careful considerations have to be made before ant actions on your CPF savings, your retirement nest.

Personally, I have transferred some of the OA savings to the SA account, and have top up SA account with cash. Will be elaborating on this in later posts as a case study for reference.


Ending note

For now, remember that 31% of your wealth are in CPF. Don't just live with it; rather, embrace and optimise it to put it to your advantage.

Are your CPF money reaching it's fullest growth potential? Are you neglecting the other significant half of your wealth?

I hope you are not.


Upcoming posts

1. More about myself - posted on 6 Jan 2017
2. Do you have a plan for early retirement - posted on 21 Jan 2017
3. My financial philosophy
4. Review of my 2016 stock investing performance
5. Why do I top up my CPF SA using cash
6. Big spending - Invisalign

Saturday, 31 December 2016

First post on the last day of 2016

Hello Everyone! This is my first post on this newly created blog.


Why I started this blog?

As a wise man once told me, "if you can't write down your ideas/ plans in words, then you don't know what you are thinking/ doing". So TA-DA! I hope this blog created using my precious New Year Eve holiday will guide myself towards my financial goals (more on this in upcoming posts). At the same time, it will be heartening if my readers will be able to benefit from my writing.


What are the content in this blog?

This blog is created mainly to record the financial goals, plans and decisions in my life. These includes:
  • Managing my expenses without compromising lifestyle quality and life experience
  • Planning my savings for mid to long-term milestone
  • Investment strategy on my stock portfolio
  • Optimising CPF for retirement and housing
I will also focus more on the considerations made (the 'why', yes I am an Enginner) to certain plan/ decision, rather than the actions (the 'what') I took. After all, who cares if I top up $7k to my CPF. I believe readers are more interested in the what is in it for me (WIIFM principle), which I will try my best to explain in my posts.


How frequent do I write?

Having read some personal finance blogs myself, I think there is a delicate balance between quantity and quality of the posts. Personally, 3-4 posts monthly seems about right for me to create posts with enough depth. 


See you guys in 2017

That's all for my virgin post. Feel free to add any comments below for suggestions on my first writing. Happy New Year everyone!


Upcoming posts

1. More about myself - posted on 6 Jan 2017
2. My financial milestone towards financial freedom
3. My financial philosophy
4. Review of year 2016 and goal setting for 2017 - posted on 1 Jan 2017
5. Review of my 2016 stock investing performance
6. Why do I top up my CPF SA using cash
7. Big spending - Invisalign